Introduction
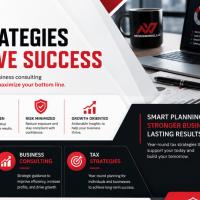
Managing taxes effectively is an important part of running a successful business. Companies need to meet their tax obligations while also protecting profits, maintaining healthy cash flow, and planning for future growth. This is where professional business consulting tax strategies can make a meaningful difference.
Effective corporate tax planning helps businesses make financial decisions before tax deadlines arrive. Rather than waiting until the end of the year to review taxes, businesses can plan ahead by evaluating income, expenses, investments, deductions, and business operations.
A well-structured tax strategy does not focus on avoiding taxes illegally. It focuses on using legitimate tax opportunities, maintaining accurate records, and making financial decisions that support the company's long-term goals.
Understand Your Current Tax Position
Before creating an effective tax strategy, a business needs to understand its current financial and tax position. This includes reviewing revenue, operating expenses, taxable income, previous tax returns, and expected financial performance.
Regular financial reviews can help identify areas where the business may be paying unnecessary taxes or missing legitimate deductions. They can also help owners prepare for upcoming tax payments and avoid unexpected financial pressure.
Accurate bookkeeping is essential during this process. Organized financial records make it easier to identify qualifying expenses and provide documentation when required.
Identify Legitimate Tax Deductions
One of the most effective ways to improve tax efficiency is to identify legitimate business deductions. Depending on the applicable tax rules, businesses may be able to deduct qualifying expenses related to employees, office operations, professional services, marketing, insurance, technology, travel, and other business activities.
However, businesses should not assume that every expense is deductible. Requirements can vary depending on the type of expense and the applicable tax regulations.
Professional business consulting tax strategies can help companies review their expenses and identify potential deductions while maintaining proper documentation.
Plan Business Expenses in Advance
Tax planning becomes more effective when businesses consider tax implications before making major financial decisions.
Large expenses such as equipment purchases, technology upgrades, employee benefits, or business improvements can affect a company's taxable income and cash flow. Reviewing these decisions in advance allows businesses to consider their financial and tax consequences.
The purpose is not to spend money simply to reduce taxes. Instead, businesses should prioritize investments that provide genuine operational value and then consider the tax treatment that may apply.
Review Your Business Structure
The structure of a business can influence its tax obligations and reporting requirements. As companies grow, their financial circumstances may change, making it useful to review whether the current structure continues to meet their needs.
Changes in ownership, revenue, investments, locations, or expansion plans may create new tax considerations.
Before changing a business structure, owners should evaluate the potential tax, legal, administrative, and financial consequences. Professional guidance can help ensure that the decision supports both current operations and long-term goals.
Use Corporate Tax Planning to Improve Cash Flow
Tax planning is closely connected to cash flow management. Businesses need enough available cash to cover tax payments while continuing to fund payroll, operating costs, investments, and growth.
Corporate tax planning can help companies estimate future tax liabilities and prepare for upcoming payments. Setting aside funds throughout the year can reduce the pressure associated with large tax bills.
Better forecasting can also help management decide when to make major investments or adjust spending.
Plan Investments and Depreciation
Business investments can provide operational benefits while also having potential tax implications. Equipment, machinery, technology, and other qualifying assets may be subject to depreciation or other applicable tax provisions.
Businesses should consider these tax rules when planning significant investments. However, tax savings should never be the only reason for purchasing an asset.
A good strategy considers the expected return on investment, business needs, cash flow, and applicable tax treatment together.
Stay Updated With Tax Regulations
Tax rules can change, and businesses that rely on outdated information may miss opportunities or make costly mistakes.
Companies should regularly review relevant tax updates and determine whether changes affect their operations. New rules may influence deductions, reporting requirements, credits, business expenses, or other areas of taxation.
Professional business consulting tax strategies can help businesses stay informed and adjust their planning when necessary.
Avoid Last-Minute Tax Planning
Waiting until tax season to think about taxes can limit a company's options. By the time a deadline approaches, some financial decisions may no longer be useful for tax planning purposes.
Year-round planning gives businesses more time to review their finances, organize documentation, evaluate investments, and prepare for future liabilities.
This proactive approach can also reduce stress during tax filing and make the overall process more organized.
Combine Tax Planning With Business Growth
Tax planning should support the company's wider business objectives. A growing company may need to hire employees, purchase equipment, expand operations, or invest in new markets.
Each of these decisions can have financial and tax implications. Including tax planning in business strategy allows owners to consider potential consequences before committing to major decisions.
This creates a more balanced approach where tax efficiency supports profitability and growth rather than becoming the only financial objective.
Work With the Right Tax Professional
Tax planning can become increasingly complex as a business grows. Professional advisors can provide an outside perspective and help identify opportunities that business owners may overlook.
A qualified professional can review financial records, assess potential deductions, evaluate investments, and help businesses understand their tax responsibilities.
The best business consulting tax strategies are tailored to the company's specific circumstances rather than relying on a one-size-fits-all approach.
Conclusion
Effective business consulting tax strategies can help companies make smarter financial decisions, manage tax obligations, and improve overall financial efficiency. When combined with proactive corporate tax planning, businesses can identify legitimate tax opportunities while maintaining compliance.
The key is to plan throughout the year instead of waiting until tax season. Reviewing deductions, expenses, investments, cash flow, business structure, and regulatory changes can help create a stronger financial strategy.
If your business wants to improve its tax planning and make better use of available opportunities, consider speaking with a qualified tax or business consulting professional. A customized strategy can help your company manage taxes more effectively while supporting long-term growth.
FAQs
What are business consulting tax strategies?
Business consulting tax strategies are professional approaches that help businesses manage tax obligations while considering broader financial goals such as profitability, cash flow, investments, and growth.
Why is corporate tax planning important?
Corporate tax planning helps businesses prepare for tax obligations, identify legitimate tax opportunities, manage cash flow, and make informed financial decisions throughout the year.
How can businesses reduce their tax liability legally?
Businesses may be able to reduce tax liability through legitimate deductions, applicable credits, depreciation, and other provisions available under relevant tax laws.
When should a business start tax planning?
Tax planning should ideally begin early in the financial year and continue throughout the year. Regular reviews provide more time to make informed decisions.
Can tax planning improve business cash flow?
Yes. By forecasting tax liabilities and planning expenses and payments in advance, businesses can better manage available cash and avoid unexpected tax-related financial pressure.
Should businesses change their structure to reduce taxes?
A business structure should not be changed solely for tax reasons. Owners should consider tax, legal, financial, administrative, and operational factors before making a structural change.
How often should a company review its tax strategy?
Businesses should review their tax strategy regularly, especially when revenue, ownership, investments, employees, operations, or tax regulations change.