Market Overview
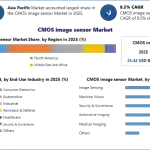
The CMOS Image Sensors Market is entering a strong growth phase as smartphones, automotive cameras, security systems, industrial automation, medical imaging and AI-enabled vision applications increasingly depend on compact, high-performance imaging technologies. According to the latest analysis by, the market was valued at approximately USD 25.42 billion in 2025 and is projected to reach nearly USD 45 billion by 2032, expanding at a CAGR of 8.5% during 2026–2032.
Market Estimation, Growth Drivers and Opportunities
CMOS image sensors convert incoming light into digital signals and are increasingly replacing conventional imaging technologies because of their high speed, low power consumption, compact size and compatibility with advanced semiconductor manufacturing. Rising smartphone camera specifications, increasing adoption of advanced driver-assistance systems (ADAS), autonomous driving, IP surveillance, machine vision, medical equipment and smart devices are supporting market expansion. The growing deployment of AI-enabled cameras is creating another major opportunity because image sensors increasingly need to capture and process visual information for object recognition, facial recognition, robotics and edge computing.
Automotive imaging represents a particularly important long-term opportunity. Modern vehicles are adopting multiple cameras for surround-view monitoring, driver monitoring, parking assistance and autonomous-driving functions. At the same time, demand for higher resolution, HDR, global-shutter technology, backside illumination (BSI), stacked sensors and low-light performance is encouraging manufacturers to develop higher-value products. AR/VR, robotics, industrial inspection, smart-home devices and wearable electronics are additional growth areas. MMR's analysis identifies Asia Pacific as the leading regional market and expects continued demand from major semiconductor and electronics manufacturing centers.
US Market Trends and Investment
The US CMOS image sensor market is benefiting from growing investment in automotive electronics, AI-based computer vision, security and industrial automation. US-based OMNIVISION strengthened its position in 2025 with the launch of the OV50X, a 50MP, 1-inch-format CMOS sensor designed for flagship smartphones and featuring TheiaCel technology for high dynamic range, low-light imaging, autofocus and high-frame-rate video. The wider US semiconductor ecosystem is also increasingly focused on domestic supply-chain resilience and advanced semiconductor manufacturing. Demand from autonomous vehicles, robotics, defense imaging, medical devices and AI-enabled cameras is expected to create additional opportunities for US sensor developers and their technology partners. As imaging increasingly becomes a core input for AI systems, investment is shifting from conventional photography toward intelligent sensing, high dynamic range and edge-processing capabilities.
Request To Free Sample of This Strategic Report ➤ https://www.maximizemarketresearch.com/request-sample/115290/
Market Segmentation: Largest Share
By Application, Consumer Electronics is expected to remain the largest segment, accounting for more than half of market revenue in 2025. Smartphones, digital cameras, tablets and other consumer devices use CMOS sensors extensively because manufacturers require compact components capable of delivering high resolution, fast image capture and low power consumption.
By End-Use Industry, Consumer Electronics represents the leading demand center, supported by the continued integration of multiple cameras and increasingly sophisticated imaging capabilities into smartphones and other connected devices.
Competitive Analysis
The competitive environment is highly concentrated, with the five leading companies—Sony Semiconductor Solutions, Samsung Electronics, OMNIVISION, STMicroelectronics and onsemi—collectively estimated to account for about 83.1% of the broader image-sensor market in 2025. Sony leads with approximately 43.4%, followed by Samsung at 20.2%, OMNIVISION at 10.8%, STMicroelectronics at 5.1% and onsemi at 3.6%.
Sony Semiconductor Solutions Corporation remains the strongest global competitor, particularly in premium mobile, automotive and industrial imaging. In October 2025, Sony announced the IMX828, an automotive CMOS image sensor incorporating a MIPI A-PHY interface directly into the sensor. The design eliminates the need for an externally mounted serializer, potentially reducing camera-system size, power consumption and heat generation.
Samsung Electronics Co., Ltd. continues to compete through high-resolution ISOCELL technology. Its sensor portfolio combines very small pixels, pixel-binning, improved autofocus and HDR technologies. Samsung's 200MP sensor developments and newer pixel architectures demonstrate the industry's movement toward higher resolution without proportionally increasing camera-module size.
OMNIVISION Technologies, Inc. is expanding across mobile, automotive, security and medical imaging. Its April 2025 OV50X introduced a 50MP, 1-inch CMOS sensor with high dynamic range and low-light capabilities aimed at flagship smartphones, highlighting the company's focus on premium imaging application.
STMicroelectronics N.V. is increasing its focus on industrial automation, robotics, security and machine vision. In October 2025, ST introduced four 5MP BrightSense CMOS sensors featuring advanced 3D stacking, global- and rolling-shutter capabilities and on-chip RGB-IR separation.
onsemi maintains a strong position in automotive and industrial image sensing, particularly for ADAS, machine vision and robotics. Its strategy centers on high dynamic range, low-light performance and sensors designed for demanding automotive environments, supporting the industry's transition toward increasingly camera-intensive vehicles.
Regional Analysis
United States: The US benefits from strong demand for automotive vision, AI, industrial automation, security and medical imaging. Its semiconductor ecosystem and growing emphasis on resilient domestic technology supply chains support long-term sensor development.
UK: The UK offers opportunities through machine vision, robotics, healthcare imaging and research-driven semiconductor development. Demand for intelligent cameras in automation and security is expected to support adoption.
Germany: Germany's strong automotive manufacturing base makes it an important market for automotive CMOS sensors. ADAS, autonomous-driving development, industrial robotics and machine vision are key growth drivers.
France: France has an important role in specialized semiconductor and imaging technologies. STMicroelectronics' CMOS image-sensor manufacturing and development activities in France support the country's position in industrial and embedded vision. ST's BrightSense sensors use advanced BSI and 3D-stacked technology manufactured at its French foundry.
Japan: Japan remains one of the most important CMOS image-sensor centers because of Sony's global leadership and the country's established semiconductor and electronics ecosystem. Continued innovation in stacked sensors, automotive imaging and high-dynamic-range technology supports market growth.
China: China is a major electronics manufacturing center and a significant market for smartphones, surveillance cameras, automotive electronics and industrial equipment. The country's extensive electronics ecosystem and increasing demand for domestically produced semiconductor components provide opportunities for CMOS sensor manufacturers. MMR identifies China, Japan and South Korea as important contributors to Asia Pacific's dominance.
Request To Free Sample of This Strategic Report ➤ https://www.maximizemarketresearch.com/request-sample/115290/
Key Players
-
Sony Semiconductor Solutions Corporation
-
Samsung Electronics Co., Ltd.
-
OMNIVISION Technologies, Inc.
-
STMicroelectronics N.V.
-
onsemi
-
Panasonic Corporation
-
SK Hynix Inc.
-
GalaxyCore Inc.
-
Himax Technologies, Inc.
-
SmartSens Technology
-
Canon Inc.
-
Teledyne Technologies Incorporated
-
Hamamatsu Photonics K.K.
-
ams OSRAM AG
-
PixelPlus Co., Ltd.
Conclusion
The CMOS Image Sensors Market is positioned for sustained expansion as imaging moves beyond conventional photography toward AI-enabled perception and intelligent sensing. The projected increase from USD 25.42 billion in 2025 to approximately USD 45 billion by 2032 demonstrates the substantial commercial opportunity available to sensor manufacturers. The strongest growth opportunities are likely to come from automotive cameras, ADAS, robotics, surveillance, edge AI, medical imaging and next-generation smartphones. In the coming years, innovations in 3D stacking, BSI technology, global shutters, HDR, ultra-small pixels, low-power architectures and on-sensor AI processing will be crucial differentiators. Companies capable of combining better image quality with lower power consumption, smaller form factors and intelligent processing will be best positioned to capture the next wave of market growth.
About Maximize Market Research
Maximize Market Research Pvt. Ltd. (MMR) is a global market research and consulting company that provides reliable, data-focused, and practical business insights. The firm serves a wide range of industries, including healthcare, pharmaceuticals, technology, automotive, electronics, chemicals, personal care, and consumer goods. Through market forecasts, competitive analysis, strategic consulting, and industry impact assessments, MMR helps organizations understand changing market conditions, identify growth opportunities, and make informed business decisions for long-term success.
Contact Us
2nd Floor, Navale IT Park Phase 3
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India
+91 9607365656
sales@maximizemarketresearch.com